Streamlining In-House Accounting Processes with AI
Artificial intelligence and generative AI may be the most important technology of any lifetime.” (Marc Benioff, CEO, Salesforce)

Traditional accounting involves a great deal of manual processing, endless menial tasks, and plenty of opportunities for mistakes and typos – all of which can mean long waiting periods for financial reports that are crucial for decision-making.

AI is changing this through advanced technologies like machine learning, natural language processing, generative AI, and intelligent automation. It can streamline accounting and finance processes, reduce human error, and empower you to make real-time data-driven decisions with greater certainty.

Many proactive businesses are already experiencing the benefits of integrating AI into their bookkeeping and accounting workflows.

Benefits of AI in accounting processes

  • Faster processing: AI dramatically accelerates routine accounting tasks, like invoice processing and bank reconciliations. These previously tedious manual processes are now completed in minutes.
  • Streamlined expense management: From a photo taken with a phone, AI can extract relevant information from receipts and other documents, categorise expenses according to company policy, and route claims for approval automatically. Reimbursements happen faster, and less time is spent chasing paperwork.
  • Greater accuracy: While manual data entry inevitably leads to mistakes, AI systems achieve impressive accuracy rates. AI also consistently applies the correct rules to every transaction and maintains complete audit trails automatically. This means less time spent fixing errors, fewer penalties, and greater confidence in your financial reports.
  • Cost savings: Reduced labour costs and fewer errors result in ongoing savings that multiply as your business grows.
  • Scalability: Automated platforms can accommodate significant growth with minimal additional resources, supporting expansion without requiring corresponding overhead increases.
  • Proactive problem-solving: AI can flag unusual patterns immediately and spot issues before they become problems, for example by predicting cash flow constraints before they occur.
  • Real-time financial visibility: With AI you can say goodbye to the traditional monthly close process and hello to continuous accounting, where accounts remain perpetually up-to-date.
  • Enhanced fraud protection: Machine learning algorithms can continuously monitor transactions for suspicious patterns, helping protect businesses from both external fraud and internal irregularities. AI can scan 100% of a company’s transactions to identify inconsistencies or potential fraud, replacing traditional manual sampling methods.

What AI means for your business

By embracing AI-driven tools, businesses can streamline financial operations, improve accuracy and decision-making, reduce costs and risks and gain a competitive edge in today’s digital economy.

If your current in-house processes still rely heavily on manual grunt work, it may be time to explore AI-enabled alternatives.

A good starting point would be to identify repetitive tasks like manual data entry or document chasing that delay your accounting processes. Start with one specific workflow: let’s say, Accounts Payable automation, training staff to shift from doing the work to reviewing the AI-generated outputs and managing any exceptions. Once you’ve got that waxed, you can start overhauling other processes.

Not a silver bullet

Experts widely agree that AI is extremely unlikely to replace accounting professionals, whether working in companies or in advisory firms. However, AI does offer great potential to transform accounting roles by automating routine tasks for enhanced efficiency and accuracy, and by enhancing analysis and decision-making capabilities.
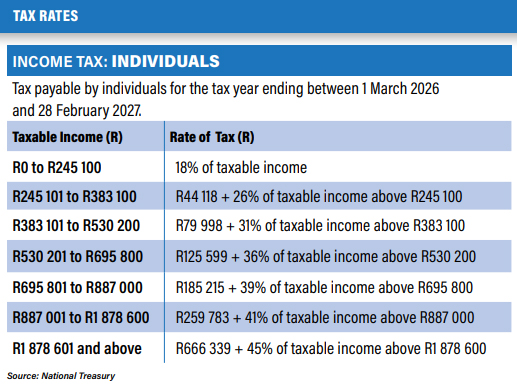


Budget 2026: Your Tax Tables and Tax Calculator

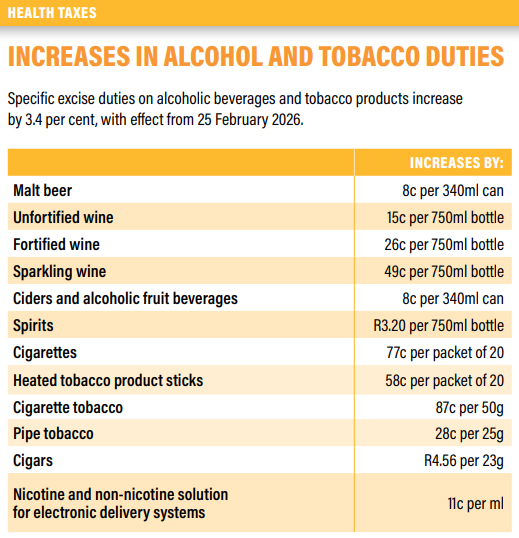
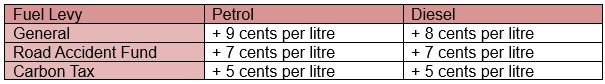
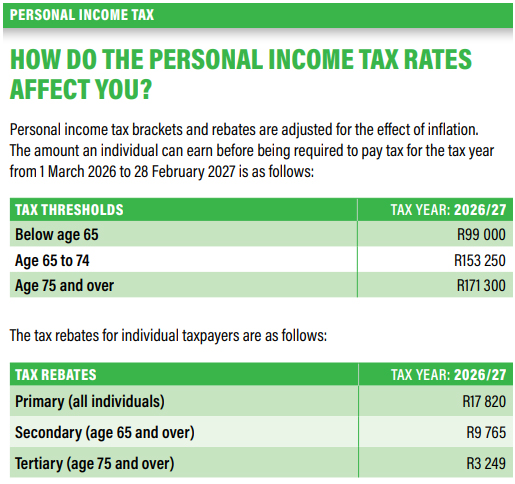
Budget 2026 has brought long-overdue relief to taxpayers by not imposing VAT or income tax hikes and by adjusting the tables for tax rates, rebates and credits for inflation. Of course, some tax hikes were always going to happen: inflation-linked increases on sin taxes took effect on 25 February already and the fuel levies also increased.

This selection of official SARS Tax Tables and other useful resources will help clarify your tax position for the new tax year. Then follow the link to Fin 24’s Budget Calculator (just follow the four-step process) to do your own calculation.

Individuals taxpayers

Source: National Treasury


Source: National Treasury


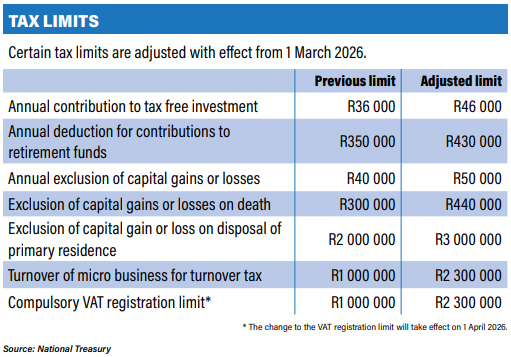
Tax limits adjusted

Source: National Treasury

Sin taxes raised

Source: National Treasury


Fuel Levy hikes

Source: 2026 SARS Budget Guide


How much will you be paying in income, petrol and sin taxes?

Use Fin 24’s four-step Budget Calculator here to find out the monthly and annual impact on your income tax, as well as what you will pay in terms of fuel and sin taxes.


Why Your Cash Flow Problems May Be Down to Your Behaviour

Never take your eyes off the cash flow because it’s the lifeblood of business.” (Richard Branson)

Ask any business analyst about recurring cash flow challenges and you’ll often hear them say, “It’s not that the business is short of money, it’s that money arrives too late or not at all.” Behind every late payment sits a human choice: a decision to delay invoicing, skip a follow-up call or assume a client will “get around to it.” These decisions aren’t random; they reflect habits and beliefs about confrontation, courtesy, and priorities.

Over time, the cost of these habits shows up in your bank account, your stress levels, and your ability to invest in growth. Changing your behaviours can change your cash flow trajectory. Here’s a breakdown of the common behavioural issues that silently undermine cash flow:

  1. Delaying invoicing

    Waiting until the end of the week, month, or project to send invoices feels courteous, especially when you want to avoid awkwardness. But every day you delay is a day your cash is “on credit.” By simply issuing invoices immediately upon delivery of goods or services, you can cut your payment cycle dramatically.
  2. Avoiding follow-ups

    Being “nice” and hoping clients remember to pay without prompting is one of the costliest behaviours in business. Assuming people will act without a reminder is sheer optimism. Don’t be afraid to send a polite reminder.
  3. Not wanting to appear pushy

    Many business owners avoid stating payment terms clearly because they don’t want to seem pushy. But it’s very possible to be both polite and firm. Clear, upfront terms eliminate confusion and reduce disputes later.
  4. Letting “good relationships” override Ts & Cs

    Being flexible with payment deadlines to keep clients happy can feel like relationship building – until you realise it’s subsidising someone else’s cash flow and squeezing yours. It also sets false precedents, erodes your negotiating power and, critically, impacts your ability to pay your own bills.
  5. Underestimating your own time

    When you don’t value your time with firm payment terms, clients often reflect that same lack of value back to you. Whether they’re acting intentionally or not, studies have shown that how you behave signals what you expect in return.
  6. Not using professional support

    Your accountant can be an invaluable asset when it comes to cash flow. An accountant can help you design invoicing systems, analyse payment patterns, and implement tools that automate reminders. This takes the emotion out of follow-ups and frees you up to focus on your craft. Talk to your accountant about structured invoicing systems and cash-flow forecasting reminders.
  7. Ignoring the feedback loop

    If clients consistently pay late, it’s a signal, not a personal slight. Asking why payment is late reveals patterns in your process, communication or terms that you can improve. Avoiding the conversation keeps you stuck in the same cycle.
  8. Fearing financial conversations

    A lack of confidence when talking about money breeds avoidance. Money conversations are uncomfortable, yes, but they build clarity and trust when done with professionalism.

New behaviour = Better cash flow

Now that you’ve identified the challenges, here’s what you can do about them.

  1. Set clear, consistent terms

    Agree payment terms upfront and stick to them. A signed agreement reduces ambiguity and gives you a basis for professional follow-ups.
  2. Automate where possible

    Use tools for billing and reminders. Automation removes the emotional resistance to chasing payments and keeps your business running smoothly.
  3. Train your team If you have staff, ensure that everyone knows how to request, follow up on and record payments. It’s vital that you’re all singing from the same hymn sheet.
  4. Track metrics – and adjust

    Ask your accountant to help you set up key performance indicators (KPIs) for cash flow, such as average days to pay, overdue ratios, and client payment patterns. Once you know what the problems are, you can take steps to fix them. If you’re only going to track one metric, make it the “cash conversion cycle” which measures, in days, how long it takes you to convert resources into cash flow. The lower the number, the better.

Cash flow is as much a reflection of your behaviour as it is of your success. Every invoice you send promptly, every follow-up you make professionally, and every firm but fair payment term you enforce tells your business and your clients how you value time, expertise and partnership.

Start treating your cash flow as a behavioural challenge, not just a financial one, and you’ll build a stronger foundation for sustainable growth.


Your Tax Deadlines for February 2026

  • 06 February – PAYE submissions and payments
  • 25 February – VAT manual submissions and payments
  • 26 February – Excise duty payments
  • 27 February – VAT electronic submissions and payments, CIT Provisional Tax payments where applicable and PIT Second Provisional Tax payments for the 2026 year of assessment.

So, You Want to Diversify? You Might Be Making a Mistake

“Any intelligent fool can make things bigger and more complex. It takes a touch of genius, and a lot of courage, to move in the opposite direction.” (Statistician and economist, E.F. Schumacher)


Diversification makes intuitive sense. When one revenue stream falters, another should compensate. When one market cools, another heats up. In theory, it’s prudent. In reality, however, as businesses accumulate products, geographies, customer segments and internal processes, decision-making slows and execution weakens. What began as risk management turns into managerial overload. The uncomfortable truth is that sometimes executing fewer things extraordinarily well, for longer than competitors can tolerate, is sometimes the path to true success.

Whether you’re selling koeksisters from your garage or leading a multinational tech behemoth, the ten pointers below are worth taking note of.

Diversification feels safer than it actually is

Diversification offers psychological comfort. It gives leaders the sense that they are “covered” from uncertainty. But safety in theory is not safety in execution. Each new product, market or channel introduces its own operational demands, regulatory requirements, customer expectations and failure points. Risk doesn’t disappear, it fragments. Instead of managing one or two critical risks deeply, leadership is forced to shallowly monitor many. The illusion of safety often masks a rise in systemic fragility.

Complexity is a hidden tax on performance

Every additional business line adds meetings, reporting layers, decision pathways and coordination costs. These costs rarely appear cleanly on an income statement, but they erode margins all the same. Management attention becomes diluted. Strategic conversations shift from “How do we win?” to “How do we keep everything from breaking?”

Focus is a force multiplier

Focused companies learn faster. They serve customers better because feedback loops are tight and clear. When something goes wrong, causes are easier to identify and fix. When something goes right, it can be scaled with confidence. Diversified organisations often struggle to replicate this clarity. Success in one unit is obscured by mediocrity in others. Focus doesn’t just improve execution, it sharpens strategic judgment.

Diversification often masks unresolved core weaknesses

One of the most under-discussed drivers of diversification is discomfort. When growth slows in the core business, expanding outwards can feel more exciting than fixing what’s broken. Unresolved issues, weak unit economics, unclear positioning, operational inefficiencies … These things don’t vanish when you diversify, they multiply to new areas. The same leadership blind spots and process failures are often replicated across a wider footprint. If you’re wondering whether diversification might be hurting you, feel free to ask for our input – sometimes a fresh perspective is all it takes.

Operational excellence doesn’t scale sideways

What works brilliantly in one context rarely translates seamlessly into another. Different customer segments require different value propositions. Different geographies demand different logistics, pricing structures and cultural understanding. Founders often underestimate how bespoke excellence truly is. Horizontal expansion assumes transferable competence – but in reality, each new area requires its own learning curve. The result can be a portfolio of businesses that are all “good enough,” but none exceptional.

Small and fast – Or big and slow?

Speed is one of the greatest advantages of entrepreneurial organisations. Diversification erodes it. As organisations grow broader, decisions require more stakeholders, more data reconciliation and more compromise. What once took days now takes weeks. Opportunities expire while you’re trying to coordinate a Teams meeting to discuss them. In fast-moving markets, this loss of velocity can be fatal. Competitors with narrower focus can outmanoeuvre diversified incumbents simply by deciding, and acting, faster.

Diversification can dilute brand meaning

Strong brands stand for something specific. They occupy a clear mental position in the customer’s mind. Diversification blurs that signal. Customers struggle to understand what the company truly excels at. Is it premium or mass? Specialist or generalist? Innovative or reliable? When brand meaning weakens, pricing power follows. What was once differentiation becomes confusion – and confusion is rarely profitable.

The most resilient businesses often look concentrated, not diversified

History is filled with companies that endured precisely because they stayed narrow. They dominated niches, controlled quality obsessively and reinvested relentlessly into their core advantage. Their resilience came not from spread, but rather from deep customer relationships, deep expertise and deep operational mastery. Concentration allowed them to absorb shocks because their fundamentals were strong, not because they were hedged.

Simplicity is not stagnation

Rejecting diversification does not mean rejecting growth. It means choosing growth paths that reinforce the core rather than distract from it. Vertical integration, geographic expansion of a proven model, or deeper penetration of the same customer segment can all drive scale without overwhelming complexity.

Don’t ask “Can we?” but “Should we?”

Most businesses diversify because they can, not because they should. Capital is available. Talent is curious. Opportunities appear abundant. But the cost of complexity is rarely paid upfront, it is paid slowly, in lost clarity, slower execution and diminished excellence. Leaders who understand this ask a harder question: what must we protect at all costs and what are we willing to walk away from?

February Provisional Tax Deadline: How to Avoid Stiff Underestimation Penalties

“Today, it takes more brains and effort to make out the income tax form than it does to make the income.” (Alfred E. Neuman, Mad Magazine Mascot)


Provisional tax is among the most confusing aspects of the tax regime – and it’s also the most heavily penalised. There are numerous declarations and payments overlapping throughout each year, not to mention a raft of rules and exceptions.

The next provisional tax deadline for the 2026 tax year (coming up on 27 February 2026) is also the trickiest and most important provisional tax deadline of the year. This is because the income estimates declared must be highly accurate. A stiff 20% under-estimation penalty can apply if the declared income estimate doesn’t fall within 80–90% of the actual taxable income.

Our professional assistance is your ticket to avoiding non-compliance and stiff penalties.

Must you pay provisional tax?

  • Companies are automatically provisional taxpayers.
  • Individuals who receive income other than a salary may also be provisional taxpayers, depending on various criteria. This includes sole proprietors and may include members of CCs and company shareholders / directors that earn income not fully subject to PAYE. SARS places the onus on you to determine if you are liable for provisional tax, so it’s best to check your status with us if in any doubt.
  • Other taxpayers include trusts and any person notified by the SARS Commissioner. Exceptions and thresholds apply in every instance, so be sure to verify with our team of tax professionals.

What is provisional tax?

Provisional tax is not a type of tax, but rather a way of paying an annual income tax liability in two or three payments during a tax year. This prevents taxpayers from facing one large tax bill at year-end when the annual personal income tax (PIT) return or corporate income tax (CIT) return is filed.

Making provisional tax payments allows you to spread the tax liability across the year. But it also creates additional administrative obligations (calculations, returns), and increases the risk of penalties – particularly under-estimation penalties.

Three provisional tax payments each year

The following rules apply to individuals and to companies / trusts with a year of assessment running from 1 March to 28 February:

  • First payment: Due within six months of the start of the year of assessment. For the 2026 year (which commenced on 1 March 2025), this was due end August 2025. This forward-looking payment is based on half of the total estimated tax for the full year, less employees’ tax already paid and any applicable tax credits and rebates.
  • Second payment (due 27 February 2026): This is retrospective and based on the total estimated tax for the full tax year, less provisional tax and employees’ tax already paid in the first period, and any applicable tax credits and rebates. The rules are far stricter with harsh penalties for under-estimating.
  • Third payment (optional): Can be made after the end of the tax year but before the issuing of the annual income tax assessment by SARS each year, typically by 30 September.

Bear in mind that SARS can ask for your estimate to be justified, so you’ll need accurate records of all source documents and calculations used. SARS can even increase the estimate if they’re dissatisfied with your amount, and this is not subject to objection or appeal.

Further penalties to watch out for

  • Late filing: If an IRP6 is filed more than four months after the deadline, SARS will consider a ‘nil’ return to have been submitted. Unless actual taxable income really was zero, an under-estimation penalty will also apply.
  • Interest charges: Interest will be levied on underpayment of provisional tax resulting from under-estimation.
  • Late payment penalty: Not making provisional tax payments on time will result in an immediate 10% penalty, regardless of whether it’s not paid at all or simply paid late.

Rely on our expert assistance

The rules of provisional tax are daunting and confusing, yet SARS holds provisional taxpayers responsible for their tax affairs.

SARS recommends that the provisional tax estimate is determined sensibly and by careful reasoning and judgement, in a mathematical manner, and using experience, common sense and all available information.


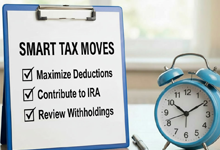
Your Year-End Tax Checklist: Smart Moves Before 28 February

“The avoidance of taxes is the only intellectual pursuit that still carries any reward. (John Maynard Keynes)

1. Boost your retirement savings

Contributing to a Retirement Annuity (RA) before 28 February can reduce your taxable income and grow your long-term wealth. If you haven’t maximised your annual tax deduction for contributions to retirement funds, this is a good moment to review it. Got any questions – ask us.

2. Top up your Tax-Free Savings Account (TFSA)

Each member of your family (even minor children) can have a TFSA and you can contribute up to R36,000 per year to each account. Interest and dividends paid from and capital growth inside a TFSA are completely tax-free, making it one of the most powerful long-term investment tools available.

3. Consider making a section 18A donation

Donations to qualifying Public Benefit Organisations (PBOs) and some other donees that are approved to issue section 18A receipts, are tax-deductible (up to 10% of taxable income). If you’re planning to give, now is a good time to do so.

4. Review your investment gains and losses

If you’ve realised capital gains this year, you may be able to offset them by realising losses on underperforming investments. This is known as “tax‑loss harvesting” and can help reduce your capital gains tax. If you’re unsure if this applies to you, we can definitely assist. There is also a CGT exclusion (up to R2 million in gains) on the sale of your primary residence so the timing of your house sale may have big tax implications (positive or negative).

5. Check your interest income

South Africans enjoy an annual local interest exemption of R23 800 (R34 500 for individuals 65 or older). If your interest income is close to or above the threshold, it may be worth reviewing where your cash is held and whether a more tax-efficient structure makes sense. Our advice here could be crucial.

6. Gather all your Tax Certificates

Make sure you have the necessary documents from your investment platforms, including:

  • Interest and dividend statements
  • Capital gains summaries
  • RA and TFSA contribution reports

These will make your tax return smoother and help avoid SARS mismatches.

7. Review medical and other allowable expenses

If you’ve had out-of-pocket medical costs or other deductible expenses, gather those records now so they’re ready for your return.

8. Provisional taxpayers: Double‑check your estimate

If you’re a provisional taxpayer, your second payment is due at the end of February. Ensuring your estimate is accurate can help you avoid penalties later.

A stitch in time saves nine

If you’d like help reviewing any of these items or want to explore opportunities specific to your financial plan, we are here to support you.

Why Doing Nothing May Be the Best Thing You Can Do

“The difference between successful people and really successful people is that really successful people say no to almost everything.” (Warren Buffett)

In a world where constant activity is seen as progress, the real high-performing leaders are doing something different. These entrepreneurs, CEOs and founders understand that not every signal deserves a response, not every problem requires an immediate solution, and not every opportunity is worth pursuing. In volatile markets, noisy feedback loops and emotionally charged leadership environments, doing nothing can be the hardest and smartest move you’ll ever make. Here’s why.

You don’t make decisions with insufficient information

If the data is weak, contradictory, or incomplete, action often locks in the wrong conclusion. High-performing founders pause to gather better inputs, test assumptions, or wait for the environment to stabilise. Acting early may feel decisive, but it increases the chances of rework and wasted capital. Don’t hesitate to consult with your accountant, or other experts while you wait to ensure all data is as complete as possible before acting.

You avoid solving problems that aren’t real yet

Many issues in start-ups resolve on their own: customer complaints from edge cases, short-term revenue dips, internal friction during growth… Founders who intervene too early often create processes, complexity, or cost for problems that would have disappeared organically. Strategic inaction prevents over-engineering.

You delay irreversible decisions

Hiring senior executives, firing key staff, pivoting your business model, or entering long-term contracts are all hard to undo. High-performing founders deliberately slow these decisions. Waiting allows emotions to settle and consequences to become clearer. Speed matters, but not when mistakes are expensive.

You prevent emotional decision-making

Founders are most likely to act badly when under stress. Losing a client, missing a target, or facing criticism is guaranteed to heighten feelings. Strategic inaction creates distance between the stimulus and the response. This reduces decisions driven by fear, ego, or the need to appear in control.

You let existing systems run before changing them

When something underperforms, the instinct is to intervene. You would be better off first asking whether the system has had enough time to work. Premature changes make it impossible to know what is actually effective. Doing nothing (for a while) is often the fastest way to learn.

You conserve focus and organisational capacity

Every new initiative pulls attention away from existing priorities. Try to recognise that your company’s capacity is limited. By choosing not to act, you will protect delivery on what already matters. This is especially important as teams scale and coordination costs increase.

You use time as a risk-management tool

Waiting can reduce uncertainty. Competitors reveal their strategies. Markets clarify. Customer behaviour becomes more predictable. Strategic inaction is often about allowing risk to resolve itself before committing resources.

The bottom line: Choosing not to act is still a decision

Doing nothing is not neutral. It must be intentional, reviewed, and time-bound. Experienced entrepreneurs track what they are choosing not to do and reassess regularly. Remember, strategic inaction works only when paired with attention and accountability.

Your Tax Deadlines for January 2026


07 January – PAYE submissions and payments

19 January – End of Filing Season 2025 for Provisional Taxpayers and End of Filing Season 2025 for Trusts

23 January – VAT manual submissions and payments

29 January – Excise duty payments

30 January – VAT electronic submissions and payments & CIT Provisional Tax payments where applicable.

Top Tips for Communicating Price Changes

“People don’t mind price increases as much as they mind surprises.” (Robert Cialdini, Psychologist and Business Author)

Costs go up and so do prices. And yet most businesses raise prices later than they should. A global study by Simon-Kucher found that less than a quarter of companies adjust prices multiple times a year as needed, with almost 30% discussing price changes only once annually, and 26% waiting for new customer tenders or contract expirations.

By the time owners take action, margins are stressed and the communication feels rushed. This is unfortunate, because studies show that a thoughtful considered, and timeous approach is the difference between a customer accepting a change and walking away.

“We’ll lose customers if we raise prices”

This fear is common, but it’s not grounded in the research. Studies from the Harvard Business Review note that when customers leave after a price change, it’s usually because the business has stayed quiet about the reason. Silence erodes trust. People assume the worst, even when the increase is modest.

The same study revealed that most customers accept changes if they still see value and understand why the adjustment exists. Communication is key. Your customers should know what costs shifted and what value you’ve added. Keep the message simple enough that a customer could repeat it back without confusion.

“Customers won’t care about the reason”

Owners often assume customers ignore explanations. Evidence says the opposite. Research from McKinsey & Company found that when companies explain the drivers behind price changes, such as rising input costs or service improvements, customer trust remains stable, even when the increase is noticeable.

People don’t need all the details, but they definitely do want you to add context. A short, fact-based explanation helps them understand that the decision wasn’t arbitrary or simply based on greed.

“If we apologise enough, customers will be less upset”

For many owners the first inclination is to apologise to the customer for the added pressure the price changes will have on their lives. Trying to soften the blow with an apology frames the price change as a mistake rather than a strategic choice. Customers may wonder whether the change is temporary or negotiable, thereby weakening your position.

This is all backed up by researchers writing in the Journal of Service Research who note that apologies work best when something has gone wrong. You can acknowledge the impact on customers without presenting the change as an error. Aim for respectful, not remorseful.

“We should wait until the last minute to avoid backlash”

Delaying the announcement doesn’t reduce resistance, it magnifies it. Short notice announcements leave customers scrambling. If the increases catch them off guard this can lead to resentment – something that’s far more likely to lead them to change supplier than the price change itself. Giving your customers timely notice shows that you respect their planning and cash flow.

You should aim to communicate price increases as early as possible. Even a few weeks’ notice can make the shift easier. Use one message delivered consistently across email, invoices, signage, and your website so there’s no confusion.

“Once we announce the increase, the conversation is over”

Many businesses make their price announcement and stop there. Whether from fear of pushback or simply a desire to not discuss it, their refusal to discuss the price changes with customers can often lead to unanswered questions, and confusion, leaving space for assumptions to grow.

Studies from Gartner highlight that businesses with strong post-announcement engagement retain more clients than those who treat the update as a one-way message. You should always be prepared for questions. Have a short script or FAQ ready. Make sure your team is aligned so they answer consistently. A calm explanation helps people adjust without feeling ignored.

“The only way to justify an increase is by adding new features”

Price increases don’t always need to come with updates or added features. Often they simply reflect the realities of the economy. Businesses that fail to keep pace eventually struggle to maintain service quality and people understand that.

This does not mean that you shouldn’t tell customers when price changes are related to improved offerings. Telling customers about upgrades gives them something concrete to weigh against the higher price. Under-explaining value is as harmful as over-explaining it.

“A single announcement will do”

People miss emails. They skim invoices. They forget dates. A single notice is rarely enough, even when well written. When a message is clear and consistent, customers don’t feel overwhelmed. Using multiple channels for communication has been shown to reduce complaints because no one feels blindsided. You should always aim to send your message through two or three channels, spaced out over time. Keep each version short and factual and make sure they each reflect the same message. Clarity prevents conflict.

What’s the takeaway?

Customers respond well when they feel informed rather than managed. They respond poorly when communication is rushed, vague, or emotional. When customers know the reasons behind changes, they are much more likely to stay loyal – even when the price goes up.