Your Tax Deadlines for October 2026

  • 07 October: PAYE submissions and payments
  • 23 October:
    • End of Personal Income Tax Filing Season 2026 for non-provisional taxpayers
    • VAT manual submissions and payments
  • 29 October: Excise duty payments
  • 30 October:
    • VAT electronic submissions and payments
    • CIT Provisional Tax payments where applicable

Win the War for Talent Without Paying Enterprise-Level Salaries

“Recognise flexibility as a selling point. Generally speaking, top talent wants the option to crunch numbers at a coffee shop or stay in their slippers at home.” (Kevin Kuske)

Every small business owner knows the feeling: a promising candidate sails through the interview process, everyone loves them … And then a bigger company swoops in with a salary offer that simply can’t be matched.

It’s easy to assume the fight for talent is over before it starts. But compensation is only one variable in a much larger equation. In addition to cold hard cash, candidates today are looking for flexibility, growth potential, purpose, and how much their work actually matters. These are all areas where lean, close-knit companies often outperform corporate giants.

Business advisors, HR experts, and small-business owners increasingly agree: the “war for talent” isn’t only won with bigger paychecks. It’s won by understanding what employees genuinely value and building an offer around it. Here are our 8 tips.

1. Lead with flexibility

Flexible work arrangements have become one of the most powerful, low-cost tools available to small employers. Staffing firm Spherion notes that many candidates weigh flexibility and growth opportunities just as heavily as salary, and that smaller companies tend to have far more room to build compelling offers around said flexibility. Data backs this up: research from the Harvard Business School found that a significant proportion of employees would accept a pay cut just to keep their remote work arrangement.

2. Make company culture your differentiator

Culture is a genuine competitive advantage for small teams. As staffing firm Beacon Hill notes, many professionals actually prefer working at smaller companies where they can see the direct impact of their work. Business owners who can’t win on salary may still win by offering something large employers structurally can’t: proximity to leadership, visibility, and a relaxed work-life balance. Small companies should lean into this rather than apologise for their size. Job postings, interviews, and onboarding should all reflect the authentic, non-corporate environment.

3. Prioritise cultural fit as much as skill

Hiring for the right personality can matter more than choosing the candidate with the most impressive CV. PureWow CEO Ryan Harwood has said he’d rather bring on someone slightly less talented who fits the culture perfectly than someone highly talented who doesn’t mesh with the team. For small businesses, where every hire has an outsized impact on daily operations, getting the right fit is doubly important.

4. Invest in growth and development

Career growth is one of the most persuasive, and least expensive, tools a small business has. The Small Business Association of Michigan points to LinkedIn’s Workplace Learning Report, which found that 94% of employees said they would stay at a company longer if it invested in their career development. Mentorship, cross-training, and covering the cost of a certification or course all send the same message: this company is invested in where you’re headed, not just what you can do for it today.

5. Recognise and reward often, informally and formally

Recognition costs a little and matters a lot. The Small Business Association of Michigan also recommends building in low- or no-cost perks. A relaxed dress code, team activities, a pet-friendly workplace, alongside regular recognition programs and small rewards to boost morale are all great ideas. Because small teams are more visible to leadership day-to-day, recognition can be personal and immediate rather than buried in an annual review cycle. A spontaneous gesture from the boss is often more meaningful to employees than the corporate version of the same action.

6. Move fast and communicate clearly during hiring

Large companies are often slowed down by layers of approval. Small businesses can turn speed into a selling point. Business.com points out that while a small business likely can’t offer the highest salaries in its market, it can offer the fastest hiring process. On top of speed, simple communication matters. Saïd Eastman, of JobsInTheUS.com, highlights how something as small as an automatic application confirmation, or a real phone number candidates can call with questions, signals respect for applicants’ time, and sets a small business apart.

7. Build the whole compensation picture, not just the base salary

Salary is only one line item in total compensation. HireHive’s guidance for small employers stresses looking at the entire compensation package, including health insurance, retirement contributions, flexible time off, and remote-work stipends. This can meaningfully close the gap between a small business’s offer and a larger competitor’s, without requiring the same payroll spend. That’s not to say salary isn’t important: the number you offer has to be realistic, of course.

8. Treat staffing as flexible, not fixed

Not every role needs to be a full-time hire on day one. Robert Half’s research into small-business staffing points back to management theorist Charles Handy’s “shamrock organization” model, blending core full-time staff with contractors and outsourced specialists, as a way to access skilled talent without committing to enterprise-level headcount costs. This approach lets small businesses bring in specialised expertise for a project or busy season, then scale back down, all while keeping the core team lean and well cared for.

The Exit You Might Not Have Considered: Selling Your Company to Your Employees

“I’ve never been a guy who’s just about getting a check, so I thought: is there a way we can keep this going, and bring others along for the ride?” (Dan Kenary, founder Harpoon Brewery, on introducing an employee ownership arrangement)

When entrepreneurs imagine an exit, they usually picture three doors: a trade sale, a private-equity deal, or a family handover. Yet there is a fourth route that is often less discussed and, for the right company, more emotionally and strategically satisfying: selling the business to the people who already know it best. When properly structured, employee ownership is a succession strategy that can deliver liquidity to the founders, stability to the staff and continuity to the customers.

Beyond the obvious buyer

For many owners, employee sales may work because they offer benefits more traditional sales do not. External bidders may promise a premium, but they can also bring integration risks, redundancies, culture changes and potentially even the wholesale dismantling of what made the company valuable in the first place. Selling to your employees, on the other hand, may offer a route towards preserving the enterprise, rewarding the workforce and allowing you to retire without feeling like you’ve sold the soul of the business.

Is it even possible?

In a conventional business sale, accountants are commonly responsible for preparing financial statements, supporting due diligence and calculating the tax implications of the transaction. An employee ownership transaction requires a much broader advisory role.

The first question your accountant (that’s us) must help you answer is the vital question of what the company is worth, and just how employees might be able to purchase it. Valuation may draw on normalising earnings, cash flow forecasts, comparable market multiples, the asset base and the particular risks of the business and ensuring accurate financial reporting. This will give you a clearer understanding of what the business is worth and whether the proposed transaction is financially sustainable.

Where employees do not have the capital to purchase a business outright, it becomes important to evaluate the options available to finance the purchase as this will impact the viability of the transaction.

How to make it happen

Once you’ve established that selling to your employees is possible, you need to decide which route to take. In South Africa, there are many different ways of doing it. Employees may acquire shares directly, either individually or through an acquisition vehicle. Some employee ownership arrangements may be structured to hold shares collectively on behalf of employees, often through a trust or another ownership vehicle. B-BBEE objectives can also be incorporated into an employee ownership arrangement.

There are many different ways to skin this cat. Each option carries different tax, governance and funding implications that change based on your company’s unique situation. Taking into account your wishes, and the financial landscape of the business, your accountant can determine exactly which of these methods is most viable.

Other considerations

Another thing which may impact the decision-making process is how taxation could be applied. Depending on how the deal is structured, founders may become liable for Capital Gains Tax on the disposal of their shares, while employees could face income tax implications if shares are acquired below market value or through certain incentive arrangements.

Trusts, debt-funded acquisitions and phased ownership transfers can all influence the overall tax outcome, making early advice essential. As your accountants, we can model different scenarios, identify potential tax efficiencies and ensure the transaction complies with the requirements of the Income Tax Act while avoiding costly surprises for both buyer and seller.

The bottom line

Selling to employees is rarely the quickest or simplest exit. It demands careful structuring, realistic valuations, appropriate funding arrangements and ongoing governance. But for founders who value continuity as much as financial return, it can provide one of the most meaningful succession strategies out there.

SARS Scams and eFiling Profile Hijacking: Taxpayers Beware

“All role players must play their part to prevent criminals from accessing taxpayers’ information.” (SARS)

Common SARS scam types

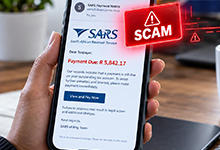
  • Phishing emails: Members of the public randomly receive false ‘spoofed’ emails, made to look as if they were sent from SARS, but which are fraudulent. Examples include emails appearing to be from returns‌@sars.co.za or refunds‌@sars.co.za, indicating that taxpayers are eligible to receive tax refunds. These emails contain links to false forms and fake websites designed to look like SARS sites, with the aim of fooling taxpayers into entering personal information such as bank account details, which criminals then extract and use fraudulently.
  • Fake SMS messages: SARS does not send *.htm or *.html attachments. Any SMS claiming to be from SARS with such attachments is fraudulent.
  • Fake WhatsApp messages: SARS will not provide links to be opened or SARS bank account details for payments on a WhatsApp message.
  • eFiling profile hijacking: Criminals gain access to taxpayers’ eFiling profiles, change banking details, and divert refunds.

What SARS will and won’t do

SARS will:
✔ Verify your personal details for telephonic engagement and authentication purposes
✔ Communicate through official SARS channels only
✔ Direct you to check your SARS profile on eFiling or the SARS MobiApp for legitimate debts
SARS won’t:
✘ Request passwords, one-time pins (OTPs), banking PINs or eFiling login credentials through email, SMS, social media or telephone
✘ Request your banking details in any communication via post, email or SMS (but SARS will verify your personal details for telephonic authentication)
✘ Send hyperlinks to other websites, even those of banks
✘ Ask for your credit card details
✘ Send *.htm or *.html attachments
✘ Provide a SARS bank account number for payments
✘ Ask you to click any link to access its website or services

What to do if you suspect a scam

Do not respond to communications that you suspect to be a scam. Simply contact us and let us provide certainty. 

We will check whether the message is part of an official SARS communication campaign or if it’s a known scam message currently in circulation. If it’s a new scam, we can report it to the right authorities.

Before you share personal information or make any payments, we can verify the communication through official SARS channels. For example, if the communication pertains to outstanding debt, we can verify this directly on SARS platforms, as any legitimate debt will reflect on your SARS profile.

How to stay safe beyond Cybersecurity Month

  • Do not open or respond to emails from unknown sources
  • Be suspicious if a message asks for personal information or creates urgency
  • Never share confidential details with unauthorised individuals
  • Never click on any link to access SARS’ website or SARS services or to verify an account
  • Only use secure internet platforms to access electronic services such as eFiling
  • Enable two-factor authentication on eFiling profiles
  • Use strong, unique passwords and change these regularly

SARS scams are becoming more sophisticated, but the rules for spotting them remain unchanged.

When in doubt, and before taking any action, contact your Tax Practitioner.

Can Business Entertainment Expenses Be Claimed Against Tax?

“To be deductible the expenditure must be: actually incurred, in the production of income, expended for the purposes of trade, and not of a capital nature.” (SARS)

Business entertainment expenses occupy a unique space in South African tax law. While they may or may not be deductible for income tax purposes under strict rules, a deduction of input VAT on these expenses is generally not allowed.

Income tax deduction? What the law says…

Under Section 11(a) of the Income Tax Act, an expense must satisfy four conditions to be deductible. It must be:

  1. actually incurred
  2. in the production of income
  3. expended for the purposes of trade; and
  4. not of a capital nature

As Judge Watermeyer explained in the landmark Port Elizabeth Electric Tramway Co v CIR case, expenses are deductible when they are “so closely linked to such acts as to be regarded as part of the cost of performing them.” In other words, you must be able to show that the entertainment was genuinely incurred for an income-producing business purpose and was sufficiently closely connected with your trade.

The “production of income” test is the key battleground in entertainment expense disputes. Expenses such as meals, venue hire, and live entertainment may be deductible if the event has a genuine business purpose, for example, entertaining clients or suppliers.

The purpose of the entertainment must be demonstrably commercial. You are required to retain sufficient records to demonstrate compliance with tax law. This might be in the form of a documented agenda or meeting notes, or a comprehensive function schedule including the date, venue, attendees, and the specific business objective.

VAT? Almost never…

Even if an entertainment expense qualifies for an income tax deduction, you generally cannot deduct input VAT on entertainment such as client meals, beverages, or hospitality. That’s because Section 17(2)(a) of the VAT Act explicitly prohibits input tax deductions on entertainment.

Entertainment is broadly defined in the VAT Act as “the provision of any food, beverages, accommodation, entertainment, amusement, recreation or hospitality of any kind.” This covers:

  • staff refreshments (tea, coffee, snacks)
  • business lunches and dinners
  • catering for staff canteens
  • annual functions (venue hire, entertainment, staff costs)
  • marketing promotions and events
  • entertaining clients at restaurants, bars and nightclubs

The exceptions

There are nine express exceptions to the prohibition on input VAT recovery for business entertainment expenses, of which two are especially important.

  1. Where the vendor is in the business of supplying entertainment (to either customers or employees), the vendor may generally claim VAT on inputs used to make its taxable supplies, provided the statutory requirements are met. SARS explains that the entertainment must generally be supplied for consideration intended to cover the direct and indirect costs, or meet the relevant open-market-value rules.
  2. Input VAT may generally be claimed on an employee’s qualifying meals and accommodation where the employee is required by their duties to spend at least one night away from both their usual residence and usual workplace, and the trip relates to making taxable supplies on behalf of the vendor.

Ducks in a row

The Tax Administration Act places the burden of proof on the taxpayer. To satisfy SARS during an audit, you must maintain contemporaneous records for every entertainment claim and retain these for at least five years from the submission date of the return in which the expense was claimed.  It’s a good idea to include the following:

  1. Date and location of the event
  2. Full names and company details of clients and staff present
  3. A specific description of the business purpose or commercial discussion
  4. Itemised tax invoices and proof of payment

Mind the audit

Professional advice is strongly recommended before claiming entertainment expenses, because a claim for entertainment expenses is likely to be flagged for investigation by SARS.

Your Tax Deadlines for August 2026

ArticleImage

  • 07 August: PAYE submissions and payments
  • 25 August: VAT manual submissions and payments
  • 28 August: Excise duty payments
  • 31 August:
    • VAT electronic submissions and payments
    • PIT Provisional Tax payments (first provisional tax payment)
    • CIT Provisional Tax payments where applicable.

Everyone Makes Them: Here’s How to Recover from a Bad Business Decision

“Failure is simply the opportunity to begin again, this time more intelligently.” (Henry Ford)

Bad decisions are a near-universal leadership experience. A 2023 study of more than 14,000 employees and business leaders across 17 countries, commissioned by Oracle, found that 85 percent of business leaders have suffered from what the researchers called “decision distress” (regretting, feeling guilty about, or actively questioning a decision made) in the past year. The same study found that 72 percent of business leaders admitted they had, at some point, given up on making a decision altogether because the available data felt overwhelming. Decision-making, in other words, is hard for everyone.

What separates leaders who recover and grow from those who stall is not the absence of bad calls. It is the quality of their response.

Own it before it owns you

The most consistent thread running through research on leadership recovery is the importance of accountability. The instinct to go quiet or minimise the impact when a decision backfires is understandable, but it can also be expensive. Once an error is noticed, credibility is far harder to restore than it would have been had the leader simply spoken plainly from the outset. The fastest route to rebuilding trust is not spin, but ownership.

Diagnose the root, not just the symptom

The second step, and one that leaders under pressure are most tempted to skip, is genuinely understanding why the decision went wrong. Surface-level post-mortems, such as “we moved too fast”, or “we didn’t have enough data” only produce surface-level corrections. Durable improvement requires tracing the failure back to its actual structural cause. Was it a flawed decision-making process? Groupthink? A blind spot about the customer? Or an incentive structure that rewarded the wrong behaviour?

Denis Liam Murphy, leadership consultant and author of The Blame Game, argues that leaders need to develop what he calls “real-time hindsight”, the discipline of reflecting immediately and honestly on what a decision revealed, rather than waiting for a formal review cycle.

The Schultz playbook: Structural recovery at scale

When Schultz returned to Starbucks as CEO in January 2008, he inherited the consequences of decisions made during a period of aggressive over-expansion. The company’s stock had declined approximately 70 percent from its 2006 peak, and 600 stores were closed across 2008 and 2009. As a Harvard Business School case study on the turnaround later documented, Starbucks had drifted from the core identity that had made it successful: the experience, the craft, and the culture.

Schultz’s recovery was not built on a single dramatic gesture. It was built on a systematic return to first principles: closing 7,100 US stores for a single afternoon in February 2008 to retrain baristas, investing in the quality of the product, and making a deliberate, public commitment to slowing down in order to grow sustainably. The recovery that followed became a business school case study not because the error was unusual, but because the response to it was disciplined, transparent, and impactful in a way that resonated with the customer base.

Build the lesson into the system

The next step in the process is to build the mechanisms which help prevent mistakes from going too far into the system. This means creating what practitioners sometimes call a “failure loop”, a deliberate process for reviewing decisions, documenting what was learned, and feeding those lessons back into future decision-making frameworks.

The practical application for any business is straightforward: after a significant misstep, write down what happened and what should have been done differently. Share it with the team. Make the lesson available to the organisation, not just the person who made the call.

Resilience is not indifference

All this advice comes with a warning. Once making errors becomes consigned to a system, it opens up the possibility of leaders accepting errors as common, processing them efficiently and therefore, becoming indifferent to their impacts. On the surface this can look like emotional stoicism, but that is neither realistic nor effective. Obviously, mistakes should be avoided at all costs.

Murphy’s research points to three foundations of genuine leadership resilience: psychology, self-care, and a support network. The first is the capacity to frame struggle as information rather than verdict. The second is giving yourself the actual time and space to recover. The third is having people around you who will tell you the truth.

None of that is soft advice. The studies show that a leader who burns through a failure without adequately processing it is actually more likely to repeat it. The goal is not to feel nothing, but to feel clearly, learn quickly, and move with intention
The Subscription Trap: SMEs are Losing Thousands to “SaaS Creep”

“SaaS spend increases without founders noticing because subscriptions renew automatically, ownership is unclear, and usage is rarely reviewed as teams change.” (Michael Pantilione)

From communication channels, to shared workspaces, AI chatbots and design services, companies are aware that they are paying more for monthly subscriptions than ever before. Research, however, suggests that most firms have no idea how deep the problem goes.

The Zylo 2026 SaaS (Software as a Service) Management Index reported that the average large organisation manages 305 separate software applications. Forty-six percent of those licences sit unused at any given time, representing approximately $19.8 million in wasted annual expenditure for the average enterprise. And it’s not just a problem affecting larger businesses. According to the report, the average British SME is estimated to waste as much as R250 000 a year on software that isn’t being actively used.

These figures reflect more than careless purchasing decisions. They are a predictable consequence of how cloud software is designed to be sold, distributed, and renewed. SaaS vendors have built their distribution models around frictionless adoption and auto-renewals. For organisations that lack formal governance over their software portfolios, this dynamic produces a cost base that grows by default, irrespective of whether the tools in question are delivering measurable business value.

Why oversight fails

The central driver of SaaS creep is decentralisation. Over the past decade, purchasing authority for software has migrated steadily away from IT and finance functions and towards individual business units. The Zylo 2026 SaaS Management Index found that business units now control 81% of total SaaS spend, while IT departments directly manage just 15%. In a small business, where procurement processes are typically informal and financial controls on software purchasing are loosely enforced, this dynamic is even more pronounced.

In short, no single department maintains visibility across the full portfolio. The Marketing team acquires its own tools, Operations purchases its own platforms, and individual team members subscribe to productivity applications on corporate expense accounts. According to Productiv, approximately 48% of enterprise applications are effectively unmanaged, meaning no one in the organisation is tracking renewal dates or monitoring active usage.

Each purchasing decision is locally rational. But collectively, they produce a software stack which is almost impossible to fully understand, manage or audit.

The renewal mechanism

Automatic renewals compound the problem. SaaS vendors have no interest in identifying underutilised licences ahead of renewal as exercising the contractual right to reduce or cancel rests entirely with the buyer.

Are there solutions?

The only way of making sure you don’t become a victim of SaaS creep, is to take control of the issue and focus on visibility, ownership, and timing. Complete visibility means knowing every active subscription in the portfolio: what it costs, who authorised it, and whether it’s being used. As your accountants, we can help you conduct a full audit of subscriptions, and put together a list of just what’s being deducted and for which service. Once you know what you are subscribed to, you can decide what to keep and which to cull.

Following on from this, it’s vital to assign someone from each team to oversee subscriptions. This person needs to make the ultimate purchasing decisions, and must maintain a complete list of subscribed services. This way, subscriptions can become an element of employee onboarding and offboarding, ensuring nothing gets lost in the system and invisible renewal costs don’t pile up in the background.

The final word

SaaS creep is, at its root, an organisational design problem. It emerges predictably wherever purchases are not carefully monitored, and where auto-renewal clauses allow costs to persist beyond the point of value. For you as a business leader, the takeaway is simple: software spend requires the same disciplined oversight as any other cost.

Provisional Tax Time: First Payment for 2027 Tax Year Due 31 Aug

“Provisional tax is merely an advance payment of a taxpayer’s normal tax liability.” (SARS)

For many taxpayers, it feels as if you’re making income tax payments all the time.

It’s not far from the truth because, in South Africa, provisional taxpayers make two compulsory payments (and possibly a third voluntary payment) each year. And that’s even before the annual income tax deadline in January of the following year, when any further tax liability will become due.

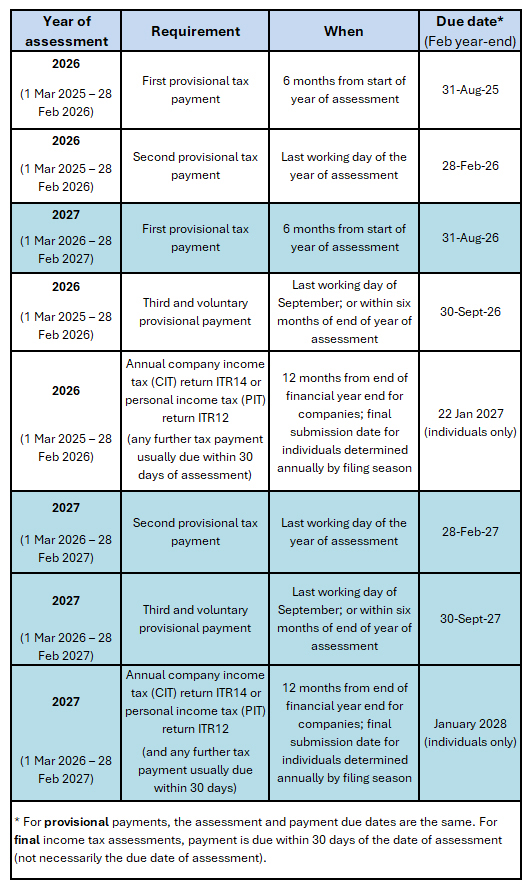
As a result, there are numerous deadlines that overlap across tax years. Yes: it is confusing, as the table below illustrates. But there’s no point throwing your arms up in the air: provisional tax non-compliance is met with some of the harshest penalties imposed by SARS.

Provisional and income tax timelines

Who are ‘provisional taxpayers’?

  • All companies except those specifically excluded
  • Any person who earns income which is not remuneration, an allowance or advance or who earns remuneration from an employer not registered for employees’ tax except those specifically excluded
  • A labour broker with an exemption certificate
  • Any person notified by the Commissioner of SARS

Why must provisional tax be paid?

Provisional tax payments are like instalments on taxpayers’ annual income tax, paid in advance and spread over two or three payments during the year. These payments are deducted against any tax owing after the year’s final income tax return is filed – at which point any further tax liability will then become due.

The objective is to prevent taxpayers from facing large income tax liabilities that are only revealed at the end of the year of assessment.

How is provisional tax declared and paid?

  • Provisional tax payments are calculated on estimated taxable income, including current taxable capital gains, for that particular year of assessment.
  • The estimates, says SARS, must be determined sensibly and by careful reasoning and judgment, in a mathematical manner, and using experience, common sense and all available information.
  • The first period estimate is forward-looking, requiring companies to estimate their taxable income for the year ahead and then to pay tax on this estimate in advance.
  • In contrast, the second period provisional return is retrospective, since by the year-end there is more certainty regarding the income for the year, and the tax due thereon.
  • These estimates of taxable income are submitted to SARS on an IRP6 return, which must be submitted by all provisional taxpayers for the first and second periods.
  • Even if you or your company owes no tax, a ‘nil’ return showing taxable income is equal to zero must still be filed on time.
  • If an IRP6 is filed more than four months after the deadline, SARS considers a ‘nil’ return to have been submitted, and unless the actual taxable income is really zero, this will result in penalties.
  • Accurate records of all the calculations and source documents used must be kept as SARS can ask for the estimate to be justified and, if dissatisfied with the amount, increase the estimate.

Your Tax Deadlines for July 2026

ArticleImage

  • 07 July: PAYE submissions and payments
  • 24 July: VAT manual submissions and payments
  • 30 July: Excise duty payments
  • 31 July:
    • VAT electronic submissions and payments
    • CIT Provisional Tax payments where applicable