Your Tax Deadlines for November 2026

ArticleImage

  • 06 November: PAYE submissions and payments
  • 25 November: VAT manual submissions and payments
  • 27 November: Excise duty payments
  • 30 November:
    • VAT electronic submissions and payments
    • CIT Provisional Tax payments where applicable.

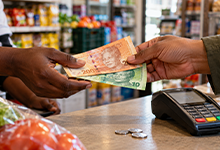
The Death of Cash is Taking Longer Than Expected and Here’s Why

“Cash remains the most popular means of payment in the economy, and we are committed to ensuring cash remains readily available and convenient.” (Rashad Cassim, Deputy Governor, South African Reserve Bank)


For years, the story seemed straightforward: smartphones, banking apps, contactless cards and instant payments would steadily push cash towards the exit. South Africa has embraced those technologies, and digital payments are increasingly normal, and yet cash has proved harder to dislodge than many predictions suggested.

Using 2024 as its base year, the South African Reserve Bank’s 2026 Cost of Cash study found that cash still accounted for about 56% of consumer transactions by volume. That doesn’t mean digital payments have stalled. It means South Africa is developing a payment system in which digital and cash transactions coexist, serving needs and circumstances for millions of people. The death of cash is taking much longer than initially expected.

Digital payments are growing rapidly

There is little doubt that South Africa is becoming increasingly digital when it comes to payments. Contactless cards, banking apps, instant payments, digital wallets and online shopping have changed how many consumers pay.

Businesses have plenty of reasons to make the switch. Digital payments can reduce cash handling, simplify reconciliation and allow businesses to accept payments without being physically present. Mastercard’s 2025 SME Confidence Index found that 90% of South African SMEs surveyed had adopted digital payments.

Online shopping provides another indication of the shift. Research from World Wide Worx, Mastercard, Peach Payments and Ask Afrika estimated that online retail would reach R159 billion in 2026, representing 10% of South African retail turnover. The digital economy is booming, but it’s doing so alongside cash.

Cash remains an everyday payment method

While cards and digital payment methods tend to account for a larger proportion of higher-value transactions, the SARB found that cash is much more important for transactions involving lower amounts. According to the study, the average cash payment was R208.44, compared with an average of R529.21 across all payment methods. For many businesses and customers, the simplicity of cash still has value.

One size doesn’t fit all

Another reason cash has proved difficult to eliminate is that South Africa’s economy is not uniform. A consumer living in an affluent urban area with reliable connectivity and several digital payment options has a very different payment environment from somebody buying goods from an informal trader or living in an area where financial infrastructure is less accessible.

The SARB’s Cash Smart Strategy recognises this difference, identifying rural towns, townships and informal settlements as areas where cash remains particularly important.

Immune to technological failure

Even in areas where the technology is generally available, breakdowns occur. Power failures, network problems and technical outages can interrupt electronic transactions, while cash sails steadily on. In a country that’s experienced repeated infrastructure disruptions, that remains a practical consideration.

Feel the burn

Digital payments can make spending feel invisible: a tap of a card or phone is barely noticeable. Cash makes the transaction more tangible, and withdrawing a fixed amount can also provide a straightforward way of controlling spending.

This means there is also a behavioural reason for cash’s resilience. Simply making digital payments available to an area therefore does not guarantee that everyone will adopt them.

The informal economy matters

South Africa’s informal economy is another important part of the picture. Many informal businesses operate on a smaller scale and may have different banking relationships, infrastructure and administrative requirements from larger formal retailers. In this sector, cash remains a practical way of accepting payment from customers without investing in additional technology, or third-party systems, which may be costly or cut into margins which are already extremely tight.

What this means for small business owners

For the average South African small business owner, cash’s resilience points to a practical lesson: being able to accept both is probably a smart choice when plotting the way forward. We can help you work out just how relevant each payment option is to your business, but here are some general rules.

  • Don’t turn away the cash customer. With cash still making up about 56% of consumer transactions by volume, a business that refuses cash risks losing a large share of everyday spending. That matters most for lower-value purchases. For businesses selling small-ticket items, cash customers are most likely the real core of the trade.
  • Build in a backup. Power cuts, network failures and platform outages can stop card machines and payment apps at the worst moment. A business that can still take cash, and keeps enough change on hand, can keep trading while competitors send customers away.
  • Offer a full range of options. With 90% of surveyed SMEs already using digital payments, being able to accept them is fast becoming the baseline. The advantage lies in combining that with cash, so that customers can pay however suits them.
  • Manage the costs. There are numerous reasons why taking cash might be attractive, particularly for businesses that operate alongside the informal economy. The savings on bank fees may be attractive, but this should be carefully weighed against the risks of holding cash, so regular banking of takings and careful record-keeping are essential.

The businesses best placed to benefit are those that treat cash and digital payments as partners rather than competitors. And it doesn’t look like that will change soon.
The Profit First Business Model: Could it Work for You?

“When less money is available to run your business, you will find ways to get the same or better results with less. By taking your profit first, you will be forced to think smarter and innovate more.” (Mike Michalowicz)

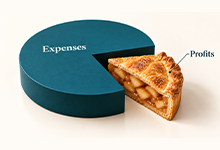
Ask most small business owners how they manage money, and you’ll hear a version of the same formula: Sales minus Expenses equals Profit. It seems logical, but it also means profit is whatever happens to be left over, which is often nothing at all. This is the trap author and entrepreneur Mike Michalowicz set out to fix when he developed the Profit First system.

Rather than treating profit as a leftover, Profit First insists it be allocated immediately, before covering a single expense. The remaining money becomes the operating budget, forcing owners to run leaner, smarter businesses. It sounds backward, even risky. But for thousands of entrepreneurs who have adopted the method, it has proven to be less about restricting growth and more about revealing which expenses were never necessary in the first place.

Flipping the traditional accounting formula

Traditional accounting treats profit as a result: revenue comes in, bills go out, and whatever survives is profit. Michalowicz argues that this formula permits overspending, because expenses expand to consume whatever cash is available. His Profit First model reorders the equation so profit is subtracted first, and expenses are calculated from what remains. The logic doesn’t change the underlying math, but it does change behaviour. And behaviour, the maths shows, determines whether a small business survives.

The envelope system, modernised

At the heart of Profit First is a system of separate bank accounts, each representing a slice of incoming revenue: profit, owner’s compensation, taxes, and operating expenses. A fixed percentage of every rand that comes in is automatically allocated across these accounts, typically on a fortnightly basis. This is essentially the classic “envelope budgeting” method used by frugal households, but applied to a business’s income. Because the operating expenses account only ever contains a capped percentage of revenue, owners are structurally prevented from overspending. The money for extras simply isn’t there.

Cash crisis or growth problem?

Data on small businesses backs up the need for a different approach. The U.S. Bank famously found that 82 percent of small business failures are linked to cash flow problems, not lack of profitability on paper. Businesses can show a healthy income statement and still run out of cash, largely because expenses were allowed to grow unchecked while net cash flows sat as an afterthought. Profit First directly targets this mismatch by making cash flow, rather than projected profit, the operating discipline.

Constraint breeds innovation

One of the more counterintuitive claims of the Profit First philosophy is that constraint improves performance rather than limiting it. When less money is available to run the business, Michalowicz contends, owners are forced to find smarter and more efficient ways of operating instead of simply spending their way through problems. This mirrors a well-documented finding in behavioural economics known as Parkinson’s Law. This is the idea that spending, like work, expands to fill the resources available. By capping the funds available for expenses, Profit First deliberately triggers a search for efficiency that a bigger operating account would never demand.

But is it the right model for your business?

The model is not universally embraced. Some accountants and financial advisors argue that Profit First’s fixed percentage allocations can feel arbitrary for businesses with irregular revenue, seasonal cycles, or high fixed costs, such as manufacturers with heavy equipment financing. Critics also note that the system does not replace the need for a solid financial forecast or a real understanding of margins, it simply complements them. For businesses with wafer-thin margins, moving money into a profit account before covering costs can create short-term liquidity strain if it’s not paired with careful planning during the transition period. It is therefore vital that you speak to your accountant before making any changes.

Baby steps

Advisors who work with the method generally recommend a gradual rollout rather than an abrupt switch. Business owners are encouraged to start with modest allocation percentages, sometimes as low as 1 percent to a profit account, and increase them quarterly as the business adjusts to operating on a leaner expense base. The goal isn’t to starve the business overnight, but to build, in Michalowicz’s words, a habit rather than an event: small, consistent decisions that compound into structurally healthier finances over time.

The bigger behavioural shift

Perhaps the most lasting impact of Profit First isn’t the specific percentages or the number of bank accounts a business uses; it’s the shift in mindset it demands. Instead of asking “how much did we make?” at the end of a difficult year, owners are asking “how do we protect profit from the very first rand?” That single reframing turns expense control from a reactive, after-the-fact exercise into a proactive discipline built into the rhythm of the business. This may be exactly the kind of structural change your business needs.

Trust Tax Season 2026 Is Now Open

“Trustees remain accountable for all tax matters of a trust, regardless of the economic activity of the trust.” (SARS)

Filing season for Trusts opened on 19 September 2026 and the closing date for Trusts to file is 22 January 2027 for both provisional and non-provisional trust taxpayers. Trustees and registered representatives should file the Income Tax Return for Trusts (ITR12T) within this period.

All registered resident Trusts and qualifying non-resident Trusts are required to submit returns in accordance with SARS’s filing requirements. For resident trusts, this obligation applies regardless of transactions or income, or whether they are active or passive, and even if they are considered “dormant”. Non-resident trusts must submit returns where they meet the applicable South African tax filing criteria.

Key changes and enhancements for 2026

The new penalty framework, which came into effect on 4 May 2026, applies to outstanding trust income tax returns for tax periods from 2024 onwards.

The ITR12T has also been enhanced to make it easier to comply with trust obligations and avoid administrative penalties for late or non-submission. These enhancements include:

  • Income, vested amounts and certain expense information has been pre-populated with IT3(t) data to reduce duplication and improve accuracy.
  • Beneficiary schedules on the ITR12T are also pre-populated using IT3(t) third-party data.
  • Beneficial ownership founder questions have been enhanced to cater for cases where the founder is a legal entity that no longer exists, in addition to deceased natural persons.
  • Tax practitioner contact details are now a mandatory field, facilitating effective communication between SARS and practitioners.

Nil returns and assessed-loss positions under the microscope

According to a 7 September press release, this filing season, “SARS will prioritise identifying, analysing, and resolving disparities detected in the submission of nil returns and assessed-loss positions.” SARS is especially keen to correct the misconception among trust taxpayers that passive trusts not actively used in the production of income may file nil returns: “The existence of passive assets does not relieve a trust from the obligation to disclose its assets, liabilities, and all relevant financial information.”

Taxpayers are reminded that all assets, including “dormant” or passive assets, must be disclosed. All income and expenditure relating to such assets (e.g. a holiday home or immovable property and the upkeep of such property) must be accurately declared. “Nil returns or assessed-loss positions must be fully supported by the trust’s records and underlying circumstances,” says SARS.

The buck stops with the trustees

SARS emphasises that “the responsibility for obtaining, maintaining, and updating accurate trust information rests exclusively with the trustees.” The Trust Property Control Act No. 57 of 1988 (TPCA) requires trustees to act with care, diligence, and skill in managing trust affairs. The “joint action rule” stipulates that co-trustees must act collectively in the administration of a trust.

Although trustees may appoint a tax practitioner to help administer the trust and fulfil its obligations, trustees remain legally liable and responsible for the trust’s tax compliance. This is not an idle threat: in some cases, trustees can be held personally liable for a trust’s tax obligations.

What you need to file an ITR12T trust tax return

Trustees should have these documents available when completing the ITR12T or when requested by SARS:

1 Trust instrument

Latest trust deed or will
Trust instrument
Certain transactions and financial flows Certain transactions and financial flows

Income sources and distribution of income; proof of any tax credits
2
3 Financial information

Annual financial statements / Annual administration accounts
Financial information
Parties connected to a trust Parties connected to a trust

Beneficial-ownership document, including detail per entity listed
4
5 Other documents

Letters of Authority and minutes/resolutions of trustee meetings
Other documents
Foreign trust documents (if applicable) Foreign trust documents (if applicable)

Controlled Foreign Company (IT10)
6
7 Mining documents (if applicable)

Mining Schedule A and B
Mining documents (if applicable)

Trustees must remember to report any changes to the registered details of a trust to SARS within 21 business days of the change. This includes changes to trustees, the representative taxpayer, contact details, physical or postal addresses, and any other registered particulars. “Failure to notify SARS of changes may constitute a criminal offence under section 234 of the Tax Administration Act.”

Have you missed this deadline?

The IT3(t) third-party data return was due for submission on 30 September 2026 for the 2026 year of assessment. This IT3(t) return must be submitted by representative taxpayers of trusts, containing “details of amounts vested in beneficiaries for a specific year of assessment. The IT3(t) return is used to populate beneficiaries’ tax returns with the amounts vested to those beneficiaries by the trust.”

If your trust missed this deadline, contact us without delay so we can assist you by taking immediate corrective action and avoiding compounding non-compliance penalties.

Deregistration of trusts

When a trust has effectively ceased to operate and has been terminated in accordance with the trust instrument and applicable law, trustees should take the necessary steps to deregister the trust with both the Master of the High Court and SARS. This is because a deregistration with the Master does not automatically mean deregistration with SARS – a trust must deregister with SARS by submitting a deregistration request, together with the required supporting documents.

We can help

Trust tax season can be complex, with significant penalties for non-compliance. Our team is experienced in keeping trusts compliant, reducing costs and preventing hassles with SARS. If you need assistance meeting the trust tax deadline on 22 January 2027, simply reach out to us. It’s the easiest way to survive this trust tax season, and those ahead.